

ATU Charity Foundation PCC
The ATU Charity Foundation PCC, a nonprofit organization, was founded in 2019 by Allgemeines Treuunternehmen (ATU) to mark its 90th anniversary. This structure serves as an umbrella organization dedicated to charitable purposes. In this sense, this legal entity serves patrons who do not wish to establish their own foundation for their charitable activities but instead integrate into the existing umbrella foundation through a dedicated segment.
Through this structure, ATU offers the opportunity to support charitable projects cost-effectively. A corresponding segment can be established with assets starting at approximately CHF 100,000.
The ATU Charity Foundation PCC is a foundation under Liechtenstein law and, as a charitable foundation, is supervised by the Liechtenstein Foundation Supervisory Authority (STIFA). The foundation is tax-exempt.
Dates and Facts
Date of establishment: 31 October 2019
Register number: FL-0002.622.721-1
Foundation Council
- Hansjörg Wehrle, President of the Foundation Council
- Märten Geiger
- Kirsten Broder-Foser
Auditors
As a charitable foundation, the ATU Charitable Foundation SV is subject to audit by a qualified and independent auditor. The auditor is appointed by the court and, as an organ of the foundation, the auditor is obliged to review once a year whether the foundation's assets are managed and used in accordance with its purposes. The auditor reports directly to the Liechtenstein Foundation Supervisory Authority (STIFA).
Purpose
The purpose of the Foundation lies in the promotion of the general public, in particular by granting economic support to natural and legal persons, institutions and organizations, pursuing activities in the support of charitable, religious, humanitarian, scientific, cultural, moral, social, sporting or ecological causes or dedicating their activities to the protection of animals.
To achieve its purpose, the Foundation, by resolution of the Foundation Council, shall establish one or more cells. Each cell is assigned a specific field of activity, which is specified in more detail in a supplementary foundation deed. The fields of activity of the individual cells must not conflict with or contradict the purpose of the Foundation.
The Foundation and all its cells are non-profit and irrevocably and exclusively common-benefit structures.
Donation Receipt
Donations and additional endowments to an existing cell or to a new cell of the tax-exempt ATU Charity Foundation PCC are deductible from taxes in accordance with Art. 47 (3) (h) of the Tax Act (SteG). Upon request, a donation receipt will be issued.
Practical Example
The Muster family has CHF 100,000 that they would like to use for charitable purposes. They would like to support the small animal shelter in their hometown with CHF 5,000 annually over the coming years. They could also envision supporting other charitable projects for the welfare and/or protection of animals.
During their lifetime, they would like to decide which projects to support and with what amount, and to actively follow the progress of these projects. Later, after their passing, their commitment is to be continued in accordance with their wishes until the funds are fully exhausted.
As a result, the animal shelter receives regular funding spread over several years. In addition, the Muster family can also support another project that they consider equally important.
In such a case or a similar one, establishing a separate structure is not recommended for cost reasons. The setup fees and administrative costs would be too high and would consume the majority of the available funds.
By making an endowment to an existing segment or establishing a new segment (see Illustration 1), costs can be saved and the funds can be directed toward charitable purposes.
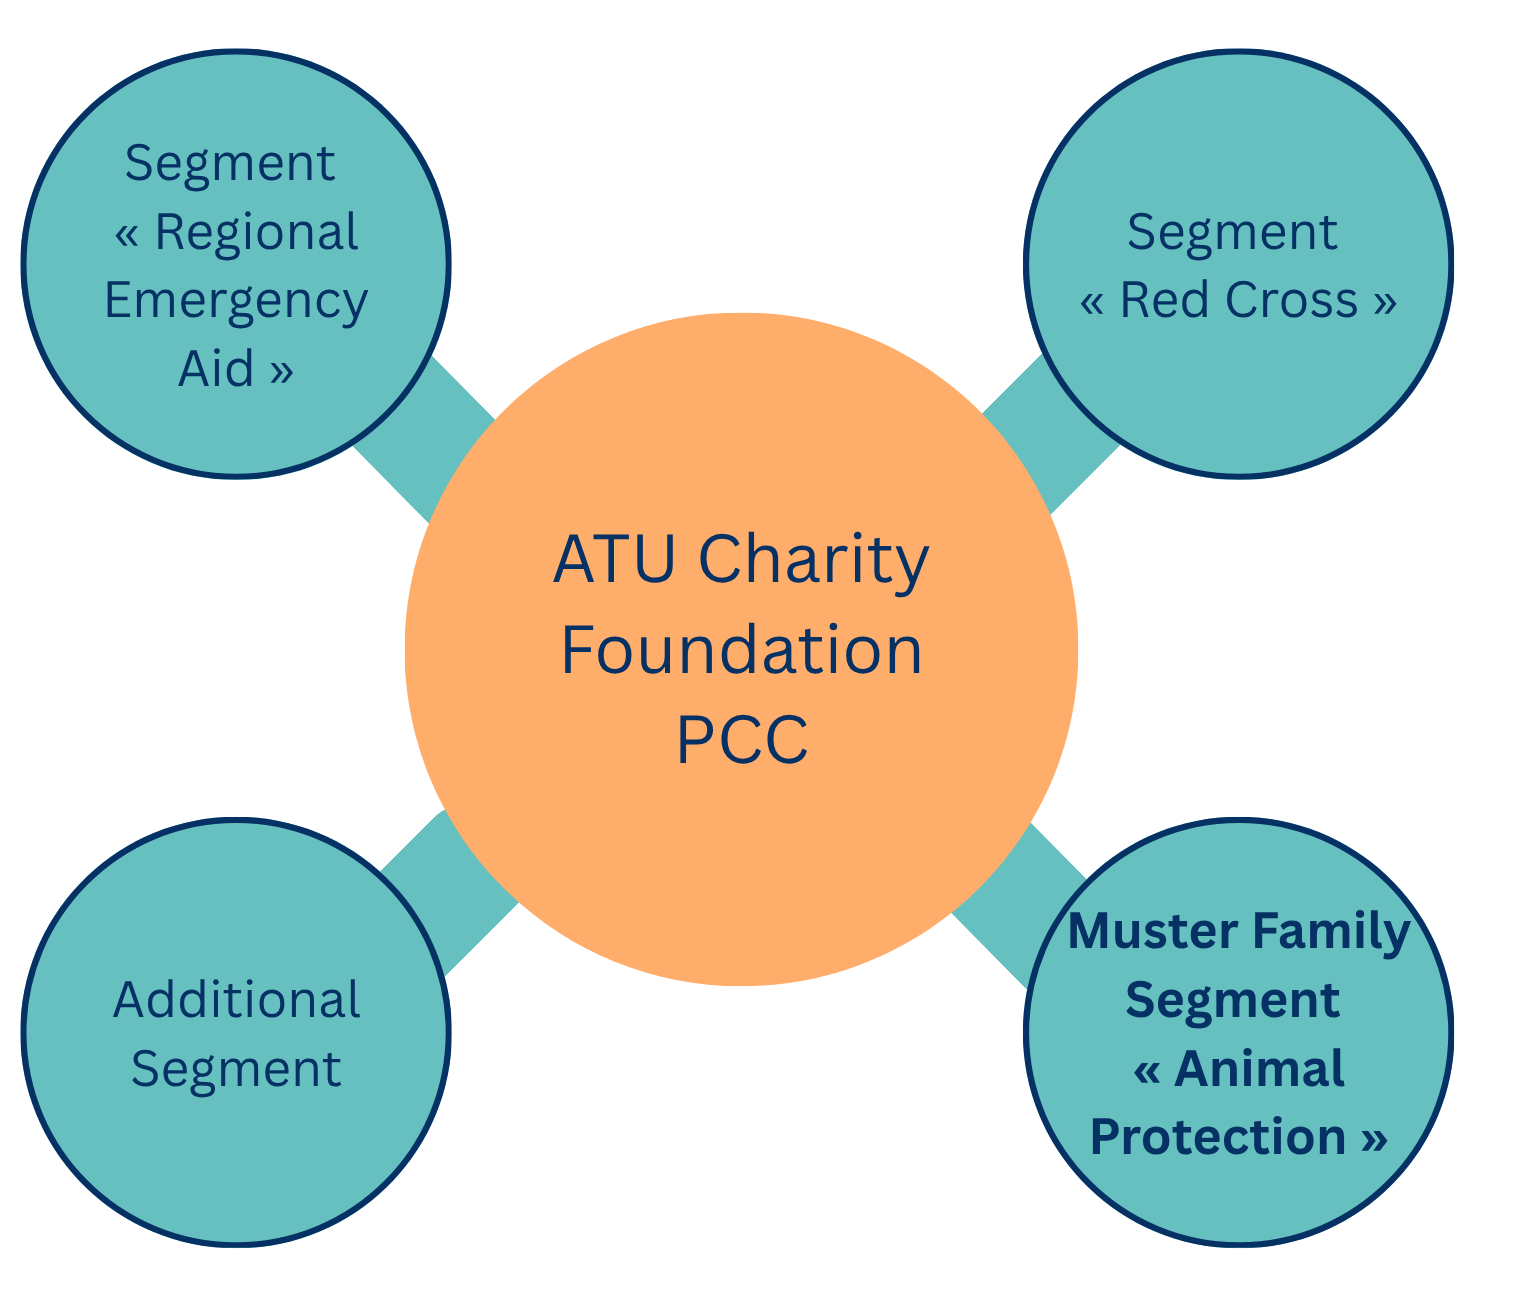
Illustration 1 – Existing segments in the ATU Charitable Foundation PCC with a new “Animal Protection” segment
Contact
Hansjörg Wehrle, LL.M.
Member of the Executive Board
Email:
Allgemeines Treuunternehmen
Aeulestrasse 5
P.O. Box 83
9490 Vaduz
Principality of Liechtenstein
Phone +423 237 34 34
Website: www.atu.li
The content of this factsheet is provided for general information purposes only and does not constitute legal advice. This article was originally written in German; this version is a translation